Employees
Account consolidation, fund allocation, retirement goals. Get clear on where you stand first, then discuss the direction that suits you.
Explore MPF planningMPF × CSPF · SFC-licensed independent WMO
From understanding where you stand,
to reviewing your allocation,
to ongoing follow-up.
Work and life keep changing.
Has your retirement allocation kept up?
Do you know which funds you actually hold?
Does your allocation still fit your goals?
When did you last review it?
Accounts, funds, contributions, goals,
scattered in different places.
See what you have today,
then you know the next step.
We go through your accounts, funds and goals, starting from what you need.
We discuss risk, fund choices and allocation direction, and explain every decision.
We review regularly, and follow up with advice when markets or your needs change.
Real case · shared with the client's consent
A senior civil servant's MPF account went from a HK$540,000 loss to a gain of over HK$1.1 million within a year and a half, a swing of more than HK$1,660,000.
| At takeover | −HK$540,650 |
|---|---|
| After one year | +HK$567,881 |
| After a year and a half (now) | +HK$1,126,127 |
| Total swing in account value over a year and a half | Over HK$1,660,000 |
*Shared anonymously with the client's consent. Account details have been blurred and are for reference only; this does not apply to every situation. Investment involves risk, and past performance is not indicative of future returns. Actual results vary with individual portfolios, contributions and market conditions.
Do the homework yourself, or talk it through first.
Pick the question you most want answered.
Start from the life you want and estimate what retirement will need.
Which fund category, and which provider, performs best? Pick the fund category you care about and compare the returns of all ten MPF providers at once, to see straight away where your fund ranks.
Look back at historical data and explore different allocations. (Chinese only)
In-depth answers to the practical questions in retirement savings.
After inflation, how long will your MPF and savings actually last? Compare three scenarios, plus how much more to save each month.
Tool results are for reference only and are not personal investment advice. Past performance is not indicative of future returns.
Not representing any bank or insurer, 100% on your side. From analysis, comparison and planning to ongoing follow-up, all free of charge.
Breaking down the practical questions in Hong Kong retirement savings, written by a licensed advisor and updated weekly.
See all articlesMPF · Retirement Gap Analysis
MPFA guidance unpacked: first four withdrawals free, guaranteed-fund terms, price risk and how to apply through eMPF.
MPF · Advanced Asset Allocation
Official MPFA data: FER spans 2.3 percentage points across 451 funds. See how a cheap vs expensive fund compounds over 30 years.
CSPF · Deep Dive
Contributions, vesting, fund choice and tax compared line by line, using CSB, MPFA and IRD sources.
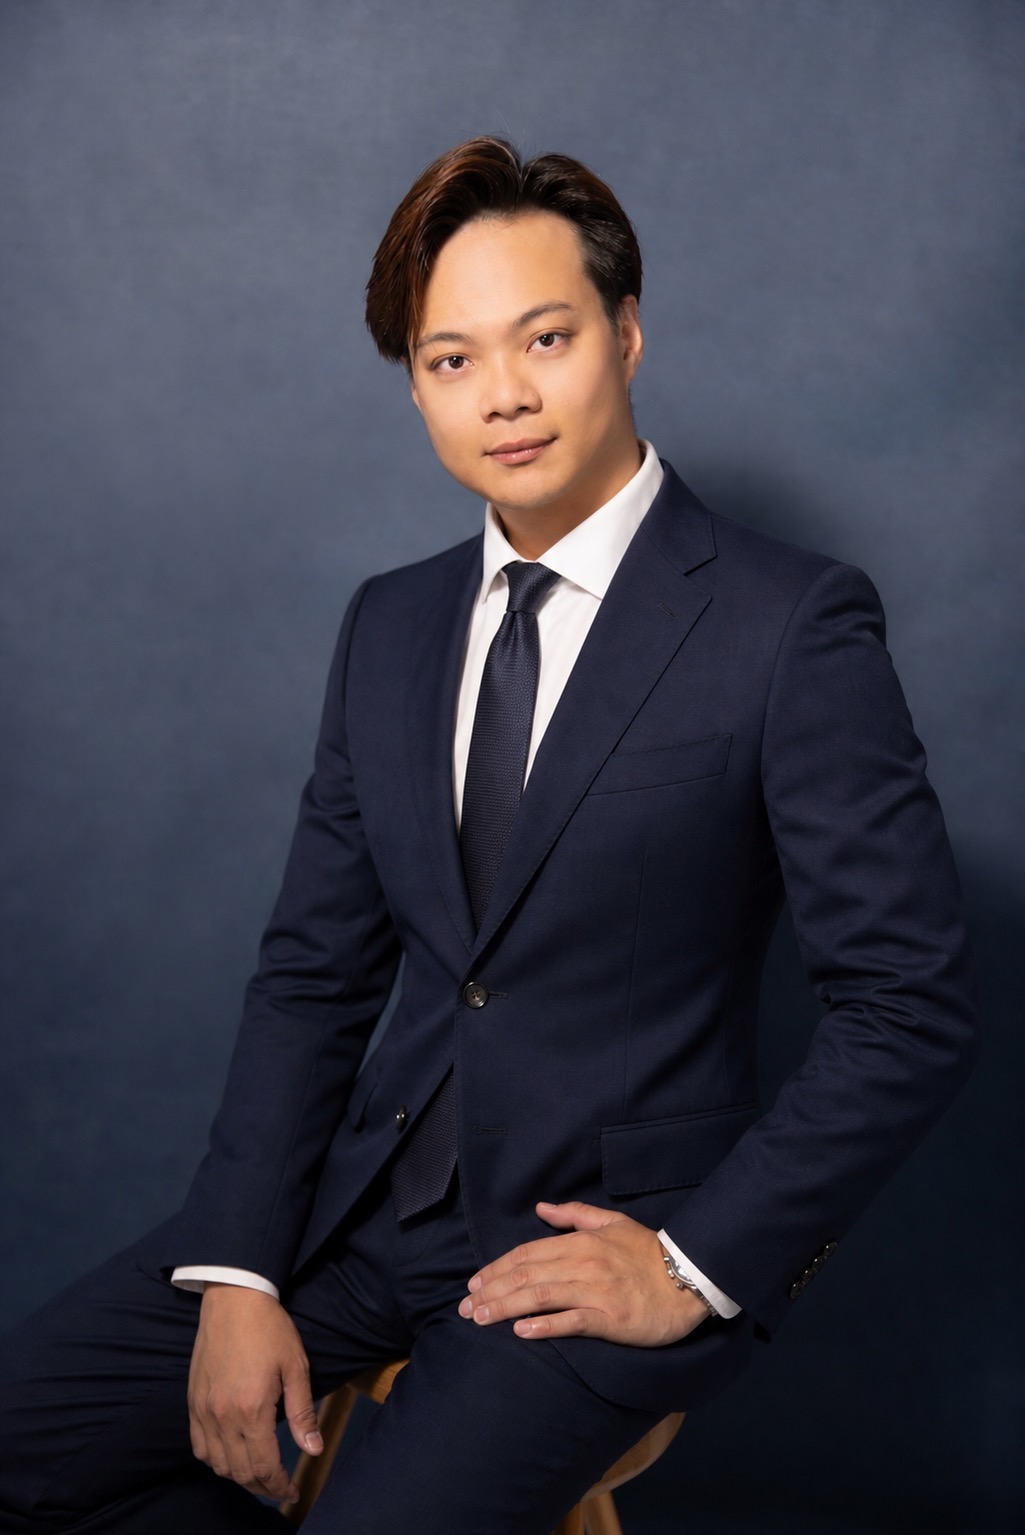
WING YEUNG / YOUR ADVISOR
Wing Yeung
Senior wealth management advisor · MPF × CSPF
I believe retirement planning should start from the life you have in mind. Understand where you stand and what you want first, then discuss the allocation together and keep following up.
As an independent Wealth Management Office, we don't represent any insurer or bank, and we give advice 100% from the client's side.
IPP International Wealth Management Limited
盈加國際財富管理 · SFC-licensed institution
Start by telling me what you want to understand. When we go further into the analysis, you can prepare your existing MPF or CSPF information as needed; before you send any documents, you can check with Wing what is actually required.
Yes. We start by understanding where you stand, discuss your goals and risk first, and only then decide whether anything needs to change. You decide at your own pace.
We discuss the allocation direction for your situation, then follow up on the portfolio and any changes that are needed. You can ask Wing about the exact arrangements in the first conversation.
Yes, 100% free. I will analyse how your MPF portfolio has performed and give you recommendations. After that you can carry them out yourself or ask me to help, entirely your choice, with zero pressure.
The CSPF (Civil Service Provident Fund Scheme) is the retirement protection the government set up for civil servants who joined after June 2000. Government contributions rise with years of service, from 5% up to 25% (the MPF employer contribution is 5%). But fund choices and management differ, so you need a separate strategy. Message me and I can break it down for you in detail.
It is never too late, but the sooner the better. Even with only 10–15 years left before retirement, choosing the right funds and adding a TVC set-up can still make a big difference. The point is to start now.
If your top tax rate is 15% or 17%, contributing $60,000 a year to TVC can save you $9,000–$10,200 in tax. Add investment returns and it looks very worthwhile over the long run. But you need to pick the right TVC plan: fund choices and fees differ a lot between plans.
I routinely cover the ten major providers: Manulife, AIA, Sun Life, BOCL (Bank of China Life), BCT, BEA (Bank of East Asia), Principal, Hang Seng, China Life and HSBC. That covers the MPF of most Hong Kong employees.
Yes. Your MPF statements and personal information are used only for analysis and are kept strictly confidential. As a licensed advisor regulated by the SFC, I am bound by strict client data protection requirements.
Register within 24 hours of your first visit for a free MPF check-up + Retirement Gap Report.
Message Wing directly on WhatsApp.
Start with the question you care about most.